
Credit Scores Explained: The Number That Quietly Shapes Your Financial Life
Your credit score is a number that quietly follows you through life, shaping decisions that affect your money in ways many people never fully understand. It influences whether you can borrow, how much you pay to borrow, and sometimes even whether you can rent a home. Yet most people have only a vague sense of what it is or how it works. Understanding your credit score — what it measures, why it matters, and how to build a good one — is one of the most practical pieces of financial knowledge you can have.
Today we continue our personal finance journey by demystifying the credit score. We will explain what it actually is, what shapes it, why lenders care so much about it, and how you can build and protect a strong one. Understanding this connects directly to the borrowing and interest rates we explored earlier in the series. As always, we keep everything clear and practical.
What a credit score actually is
A credit score is a number that represents how reliable you are likely to be at repaying money you borrow. It is, in essence, a summary of your track record with credit, boiled down into a single figure that lenders can quickly read.
Think of it as a financial reputation. Just as a person might earn a reputation for being reliable or unreliable based on their past behavior, your credit score is a reputation for how you handle borrowed money, built from your history of borrowing and repaying. A higher score signals to lenders that you are likely to repay reliably; a lower score signals more risk.
The exact scale differs by country and provider. In the United States, the widely used FICO score runs from 300 to 850, where higher is better. Other countries use their own systems and ranges, but the underlying idea is the same everywhere: one number summarising how reliably you repay.
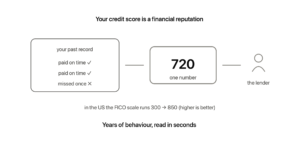
This number is calculated from your credit history — the record of your past borrowing and repayment. Companies gather this history and use it to produce your score, which lenders then check whenever you apply to borrow. It is a shorthand that lets a lender assess your reliability in seconds, without knowing anything else about you.
Why lenders care so much
To understand why your credit score matters, recall what we learned about interest rates and risk and return. When a lender lends money, they face the risk that they will not be repaid — and as we saw, risk must be rewarded, and greater risk demands greater reward.
Your credit score is how lenders judge that risk. A high score suggests you are low-risk, so lenders are happy to lend to you, and to do so at lower interest rates, since they feel confident of repayment. A low score suggests higher risk, so lenders may charge higher interest rates to compensate, or may decline to lend at all.
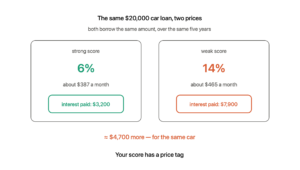
Here is what that means in actual money. Imagine two people borrowing $20,000 for a car over five years. The one with a strong score is offered 6% and pays about $387 a month, or roughly $3,200 in total interest. The one with a weak score is offered 14% and pays about $465 a month, or roughly $7,900 in interest. Same car, same loan, same five years — but one pays around $4,700 more, simply because of a number. (These figures are an illustration; real rates vary.) Over a lifetime of borrowing for cars, homes, and more, this difference can add up to an enormous amount of money. Your score, quite literally, has a price.
What shapes your credit score
Credit scores are built from several factors drawn from your financial behavior. While the exact formulas are complex and vary, the main ingredients are well understood, and knowing them shows you how to build a good score.
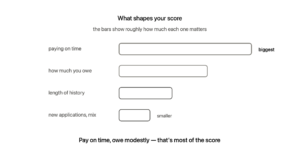
Payment history. The most important factor by far is whether you pay your bills on time. A consistent record of on-time payments builds a strong score, while late or missed payments damage it significantly. Reliability is everything.
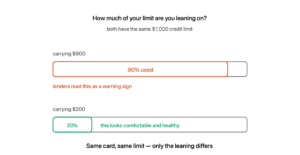
Amounts owed. How much you owe relative to how much credit you have available also matters — this is often called your credit utilisation. Say your card limit is $1,000. If you are carrying $900, you are using 90% of what is available, which lenders read as a warning sign. If you are carrying $200, you are using 20%, which looks comfortable and healthy. Same card, same limit — the difference is how much of it you are leaning on.
Length of history. A longer track record of responsibly handling credit generally helps, because it gives lenders more evidence of your reliability. This is why starting early and keeping good accounts open can be beneficial.
Other factors. Things like how recently you have applied for new credit and the variety of credit types you handle can also play a role. But payment history and amounts owed are the heavyweights.
How to build and protect a good score
The good news is that building a strong credit score comes down to a few sensible habits, all within your control. There is no trick — just consistent, responsible behavior over time.
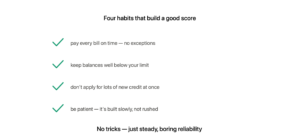
Pay every bill on time, without exception, since payment history is the single biggest factor. Setting up automatic payments or reminders can help ensure you never miss one — and this is where the budgeting habit pays off twice, because knowing your money is planned makes missed payments far less likely. Keep the amount you owe well below your available credit limit, using only a modest portion of what is available to you. Avoid applying for lots of new credit in a short period, which can signal risk. And be patient: a good score is built over time through steady, reliable behavior, and cannot be rushed.
An emergency fund also protects your score in a way people rarely notice. When a surprise cost arrives and you have savings, you pay it and move on. Without savings, that same cost often becomes a missed payment or a maxed-out card — the two things that damage a score most.
It is also wise to check your credit history periodically for errors, since mistakes can unfairly lower your score. In many places you can review your credit record, and correcting any errors you find protects your score. Protecting your score is as much about vigilance as about good habits.
When your score is low
If your credit score is low, or if you have no credit history at all, it is important to know that this can be improved. A score is not a permanent judgment; it reflects your recent behavior and can change over time.
Rebuilding a score follows the same principles as building one: pay everything on time, reduce what you owe, and be patient as your consistent behavior gradually improves the picture. Negative marks fade in importance over time as they are replaced by a growing record of reliability. For those with no history, starting to build one responsibly — and demonstrating reliable repayment — establishes a score over time.
The key message is one of hope and agency: wherever you stand today, steady, responsible habits will improve your score over time. It rewards patience and consistency, which means it is within almost anyone’s power to build.
Why this matters to you
Your credit score has real, tangible effects on your financial life, often in ways that are invisible until they matter. It shapes whether you can borrow for major life purchases like a car or a home, and crucially, how much that borrowing costs you. A strong score can save you a great deal of money over a lifetime through lower interest rates, while a weak one can cost you dearly.
Beyond borrowing, your score can influence other areas of life, such as renting a home, since landlords sometimes check it. This quiet number, in other words, can open or close doors well beyond loans, making it worth understanding and protecting.
Most of all, understanding your credit score puts you in control of something that would otherwise control you. Instead of a mysterious number that shapes your options from the shadows, it becomes something you understand and can actively build. By practicing a few sensible habits — paying on time, borrowing modestly, staying patient — you can build a strong financial reputation that serves you throughout your life, saving you money and opening opportunities. That understanding, and the control it brings, is genuinely empowering.
Difficult words, made simple
| Term | Plain-English meaning |
|---|---|
| Credit score | A number showing how reliably you repay borrowed money |
| Credit history | The record of your past borrowing and repayment |
| Payment history | Your track record of paying bills on time |
| Credit utilisation | How much of your available credit you’re currently using |
| Credit limit | The maximum amount you’re allowed to borrow |
| Creditworthiness | How reliable you appear as a borrower |
| Default | Failing to repay money you borrowed |
| Interest rate | The cost of borrowing, often shaped by your score |
The big takeaway
A credit score is a number representing how reliably you repay borrowed money — a financial reputation built from your history of borrowing and repaying. Lenders care because it lets them judge risk in seconds, and it directly affects how much borrowing costs you: on the same $20,000 car loan, a strong score might mean $3,200 in interest while a weak one means nearly $7,900.
Your score is shaped mostly by paying bills on time and by keeping what you owe modest, along with the length of your history. Building a good score comes down to consistent, responsible habits: pay on time, borrow modestly, avoid too much new credit, and be patient. Wherever you stand today, steady behavior improves your score over time. Understanding it puts you in control of a number that quietly shapes your financial life — and can save you a great deal over a lifetime.
Sources
This article explains widely taught principles of how credit scores work. Specific scoring systems, ranges, and rules vary by country and provider, and the loan figures used are illustrative examples. It is general educational information, not financial advice.
Related reading: Interest Rates Explained and Credit Cards and Managing Debt.
Growmmunity publishes explanations, not financial advice.